Frozen-Pipes-Criple-Texas-min

Frozen Pipes Criple Texas

As Texas recovers from the arctic blast, pipe problems will remain an issue for many Texans. San Antonio alone reported more than 10,000 claims related to frozen pipes or pipe leaks. In Houston, city and county leaders on Friday said tens of thousands of area residents and business owners suffered burst water pipes or other damages from the winter storm, Uri, resulting in property damage likely costing tens of millions of dollars. A federal disaster declaration, which President Joe Biden said he will sign, could free up money to reimburse affected residents, as well.

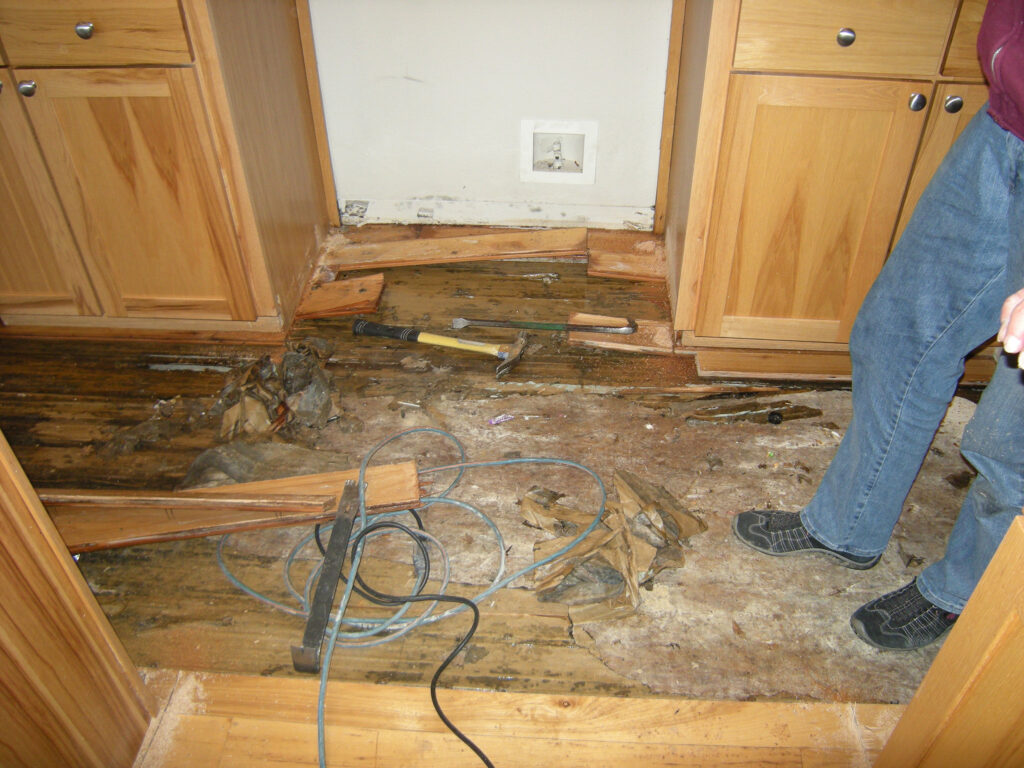
When it comes to water leaks from broken or frozen pipes, our attorneys have in-depth experience handling these types of denied homeowners insurance claims. One client of ours, from the Dallas area, experienced a pipe burst in their upstairs bathroom which caused water damage to the first floor of their home.

Initially, their insurer (Farmers Insurance) sent an adjuster that determined that the damage could be repaired for the cost of their deductible. When our client’s questioned the insurance about this estimate, they hired an engineer to back up their first adjuster’s findings. Unable to make the necessary repairs with this amount, our client hired us to represent them and go after their insurer for a full recovery.

Our third-party adjustor found damage to the flooring and a kitchen cabinet, thousands of dollars in damage, that the original adjuster and engineer missed. Upon receipt of those findings, we filed suit with Farmers Insurance. With the evidence collected our case was stronger than the insurer wanted to contend with and ultimately settled out of court. Originally the insurer had agreed to cover the cost of the sheetrock, but after our findings, we were able to get them to pay enough to cover the cost of the damaged flooring and kitchen cabinetry. We were able to secure the essential funds for our client to make the necessary repairs to their home and get back to life as usual.

Texas does not see cold weather like what we just experienced. Our infrastructure was not ready for the intense cold. Many homes experienced catastrophic damage to their homes and property. To battle the slew of misinformation out there, here are a few things you should know about frozen or broken pipes in general.

What You Should Know

Homeowners insurance typically covers damage that results from broken pipes. 

What if my house is flooding? Water damage from a pipe burst is typically covered under a homeowner’s policy. Flood water damage, including excess groundwater, is not covered by a typical homeowners or renters insurance policy. The homeowner needs a separate flood insurance policy to claim damage on the effects of water egressing or discharging back into the home.

What if I rent? Renters insurance should cover water damages to your personal property from broken or ruptured pipes, but if damages are caused by water backing up in a drain or suction pump you will not be covered without having purchased additional coverage. Renters do not usually need to worry about the damage to their homes. That should be covered by their landlords’ insurance policy.

What if my ceiling collapses? Homeowners insurance does cover sudden and accidental water damage that may result in interior damage. One reason that insurers may deny a claim would be if a filer knew about prior structural decay or damage in the home before the collapse.

Texas Property Insurance Lawyers

Has your homeowner’s or commercial business insurance water claim been denied? We can help. Representing thousands of clients against big insurance companies, our insurance claims attorneys aggressively protect the rights of the policyholder. Our consultations are free, and you owe us nothing until we win your case. Contact us today.

Hailstorm-Damage-Puts-Faith-in-Question

Hailstorm Damage Puts Faith in Question

The 2016 storm season was the most expensive storm season on record for Texas. On March 17th, 2016 Arlington, Texas experienced no less than six recorded hailstorms, the largest of which generated hail two-and-a-half inches in diameter. The hazardous weather system began Thursday morning, dropping huge pieces of hail and grounding flights out of DFW Airport. This was a monster storm that damaged many homes in the area, our client being one of those homeowners.

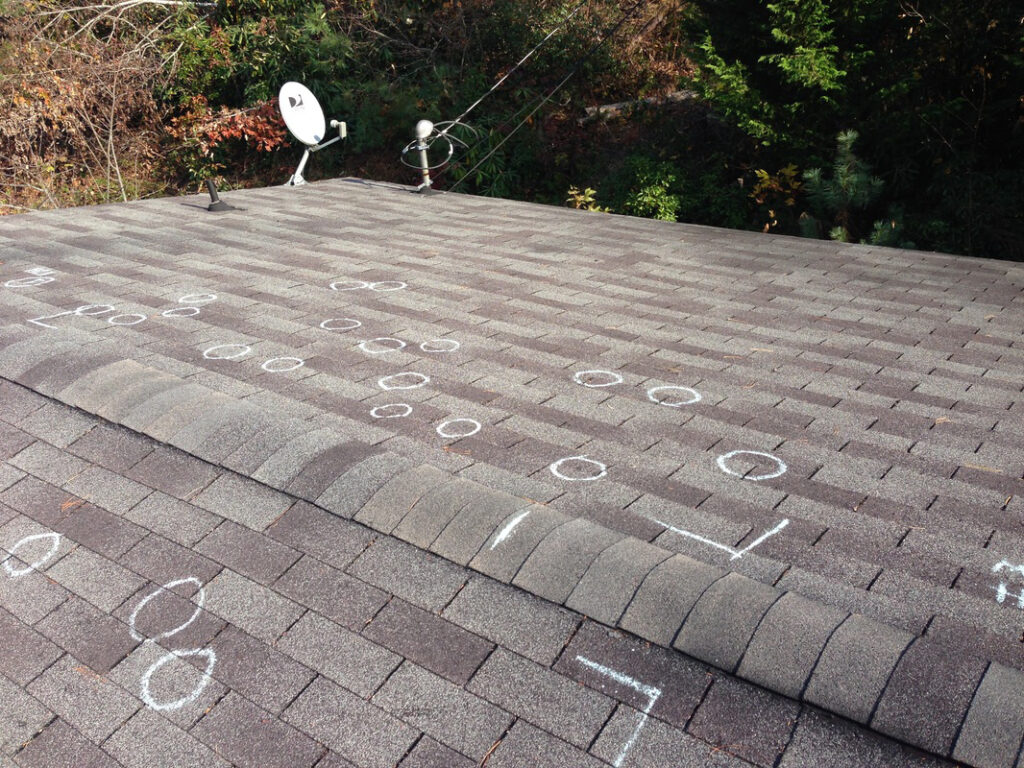
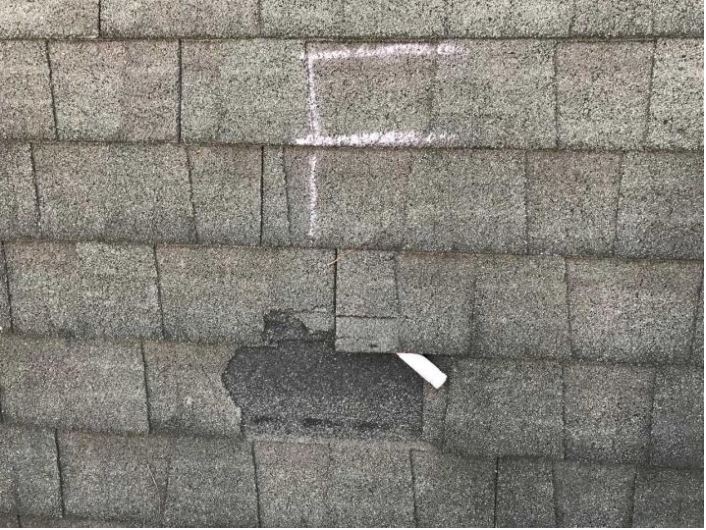
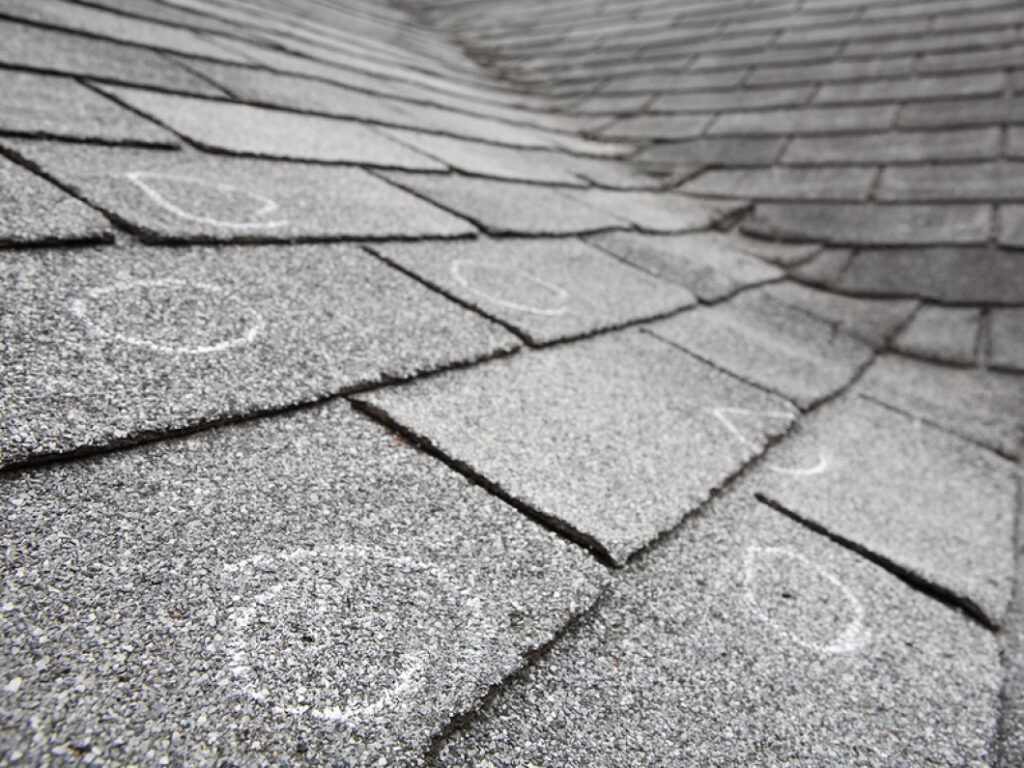
The roof damage was so severe that our client submitted a homeowners insurance claim through his insurance provider, State Farm. After filing the roof damage claim, the insurer sent out their adjuster who inspected the property damage and determined there was none or below our client’s deductible. Blindsided by his insurer’s stance, our client hired us and invoked appraisal for their case. The appraisal award came back at 80,000 times the amount of damages originally assessed by State Farm.

State Farm paid most of the award. To collect the remainder of the award and interest and attorney fees, our client pursued his insurer by filing suit, declaring his insurance company had acted in breach of contract and violation of Chapter 541 of the Texas Insurance Code, the Texas Deceptive Trade Practices Act (DTPC), and the Texas Prompt Payment of Claims Act (TPPCA). To guard their profits, insurers every so often commits deceitful practices, deliberately distort their policy language to avoid paying a claim, use absurd delays to avoid resolution of a claim, or make frivolous demands about proof of loss. This is called a bad faith insurance practice.

Our client’s insurer responded with a motion for partial summary judgment on all our client’s claims as a means of staving off breach of contract and TPPCA pursuits based on the Texas Supreme Court decision in Ortiz. State Farm argued that they had paid the award and therefore there was no breach of contract or extra-contractual claims left to pursue.

Is It Bad Faith, Bad Luck, or Both?

For the statutory bad faith claim to stick, our client had to show a breach of contract by his insurer. The insurer contends that a breach of contract is a prerequisite to statutory bad faith, yet policyholders argue a breach of contract is only a prerequisite to bad faith when the claim is not covered.

Generally, there can be no claim for bad faith when an insurer has promptly denied a claim that is not covered. However, failure to show a breach of contract does not alleviate a policyholder’s bad faith claims. What this means is the insured must show coverage, not a breach of contract. It is undisputed that our client’s claim under the policy was covered. The insurer did find damage, below the deductible when the claim was initially adjusted.

The only fair and rational analysis of the law that does not offend common sense or public policy is one that preserves an insurer’s responsibility to deal with an insured in good faith when the insured’s claim is covered. Our client’s insurance providers manipulation of the law would allow them to ignore their responsibility and systematically delay, deny, or underpay insurance claims until the insured hires an attorney and sends a pre-suit notice letter suing for breach of contract and bad faith, then to simply invoke appraisal, pay the award, and weaken the insurer’s contractual liability but also its statutory liability for bad faith acts and the adjustment process.

At the hearing, our attorneys argued the above and pointed out that an appraisal award that is 80,000 times higher than the amount first assessed by State Farm, and the unilateral (line-item veto) of certain damages in the award, amounted to breach of contract and bad faith. The court agreed and denied State Farm’s summary judgment on all grounds.

Texas Property Insurance Lawyers

Has your homeowner’s or commercial business insurance claim been denied? We can help. Representing thousands of clients against big insurance companies, our insurance claims attorneys aggressively protect the rights of the policyholder. Our consultations are free, and you owe us nothing until we win your case. Contact us today.

Texas-Size-Hailstorm-Crushes-Conroe

Texas Size Hailstorm Crushes Conroe

Hail damage is the number one cause of property damage in the US. In 2019-2020 alone the State of Texas has seen more claims related to hail than most states. Severe property damage occurs when a dangerous storm strikes a highly-populated area with hail larger than an inch or more in diameter. Baseball-sized hail (3.5 inches across) is a common occurrence in the Lone Star State and creates devastation in our communities.

On March 18th, 2018, a major hailstorm blew through Montgomery County, impacting Conroe and the surrounding areas. Our client, an 80-year-old retiree, witnessed extensive hail damage to his roof.  As the original owner of the home, built-in 2006,  our client never imagined that he would have to eventually have to face down a hailstorm-homeowner insurance claim. Relying on his faith as a long-term customer with Safeco insurance (12 + years), he filled a hailstorm insurance claim and to his shock, the claim was denied. At that point he knew, he’d be facing down the insurance company in an effort to cover his losses.

The insurance company sent three different inspectors to review the property damage. Each one ended up blaming the manufacturer of the shingles on the roof, calling the product defective. Ironically, these were the same shingles that had been on the house since it was built. The very same shingles Safeco insured the home with, and routinely collected a premium from our client on. Next, the insurer would deploy extensive stalling and delay tactics to keep from paying our client’s insurance claim. Shortly thereafter, fed up and frustrated, our client hired us to pursue the insurer.

Our team of engineers independently reviewed the property damage and determined the roof damage was not due to defective shingles, but actual storm damage. A series of depositions would cast the case in a new light. With the case set to go to trial and the insurer finally realizing the errors of their ways and the poor treatment of our client and his terminally ill spouse (who passed away during the pendency of the case), the insurance company chose to settle the case. This meant that our client would receive the funds necessary to have a new roof installed on his home.

The Law of Hailstorm Damage Insurance Claims

Homeowners that do not file within the statute of limitations can miss the chance to recover their losses, indefinitely. This timeframe is often two years from the date of the incident, even though a case-by-case or a policy-by-policy analysis of the statute of limitations is required.

Our expert attorneys have seen thousands of cases where insurance companies have delayed, underpaid or simply denied the legitimate claims of the policyholders they insure causing an unfathomable amount of emotional and financial damage. In Texas, this is an illegal practice and insurance companies can be held liable for acting in bad faith. Insurance companies participating in these illegal activities can be sued for up to three times the damages reflected in the insurance claim.

Texas Hail Damage Attorneys 

Has your homeowner’s insurance claim been denied? We can help. Representing thousands of homeowners against big insurance companies, our home insurance claims attorneys aggressively protect the rights of the policyholder. Our consultations are free and you owe us nothing until we win your case. Contact us today.

Twice-Denied-Homeowners-Insurance-Claim-Leads-to-New-Roof

Twice Denied Homeowners Insurance Claim Leads to New Roof

Property damage may include damage to your home, your patio furniture, your fence, your mailbox, or any other belonging to your property. How much you may be able to recover for your property damage can be determined by proof of replacement value, repair costs, the inability of use until fixed or replaced.

Having a roof insurance claim denied is common. Luckily, a roof damage claim denial does not have to be the last word. Understanding the insurance claim process and how to challenge an insurance denial is a valuable skill for every homeowner. In most situations, your homeowner’s insurance covers roof damages due to a storm. You can expect a claim rejection letter if the peril is excluded by your homeowner’s insurance policy. Knowing what your homeowner’s insurance policy excludes is very important. Some standard homeowners insurance policies (HO-3) cover common disasters, but not everything. Some insurance policies have separate wind and hail damage deductibles. Make sure to read your policy carefully to understand what damage is covered.

It Was the Other Storm’s Fault

In the spring of 2016, the Spring, Texas area experienced a wind and hail storm that damaged the roof and exterior of our clients’ home. Our clients, one a 40-year plus emergency room nurse, filed a homeowners insurance claim with their insurer who sent out an adjuster who wrote the damage off as minimal and failed to cover the damage to the roof. The adjuster claimed the roof damage was less than $1000 and under the deductible, even though other houses in the neighborhood received new roofs due to the wind and hail damage. Our clients trusted the results the insurance company provided them with and did not pursue any action after the initial insurance claim denial.

Then came Hurricane Harvey a year later and the roof leaks that followed. Our clients filed another homeowners insurance claim to which their insurance company responded by sending out another adjuster, who came back telling them the roof leaks were a result of previous damage and/or wear and tear, not the storm. That meant the insurance company most likely misrepresented the scope of damages during the first claim back in 2016. Having experience with one denied homeowners insurance claim already, our clients called us to take their case. Our own third-party adjuster concluded the damage from the hailstorm in 2016 that went unrepaired was exacerbated by Hurricane Harvey and ultimately the fault of the insurance company for not fixing the repairs before the hurricane’s impact.

Bad Faith Insurance Claim Seeks Redemption

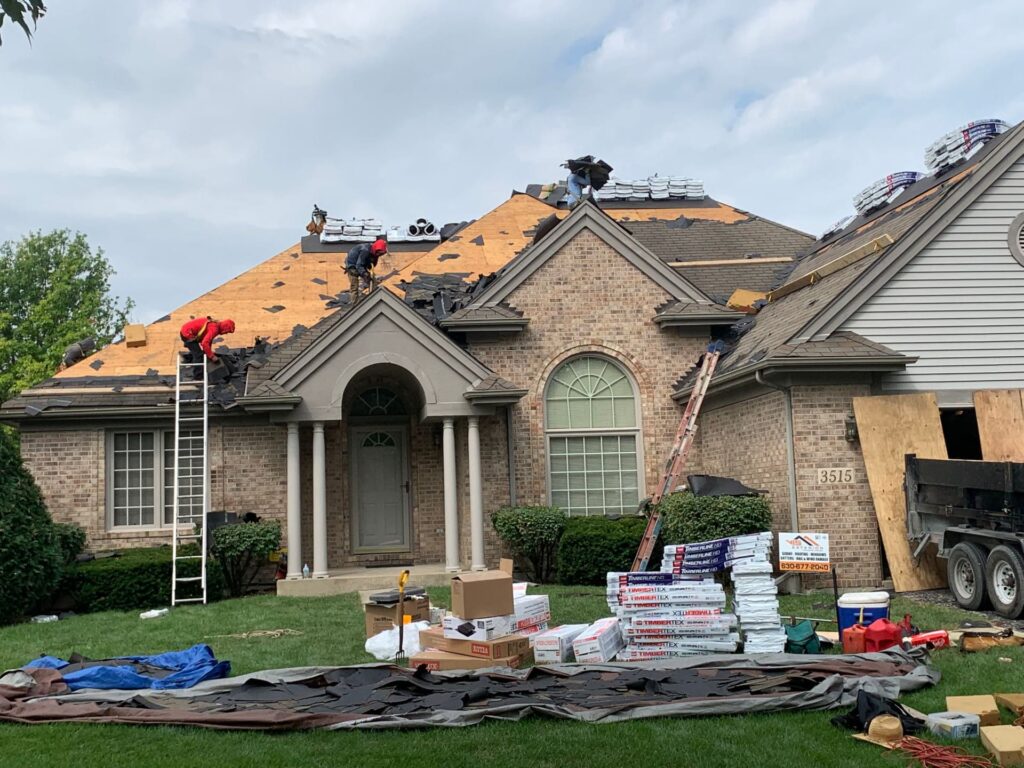
If the insurance company had fixed the repairs to the home from the initial claim, the damages inflicted during Hurricane Harvey would have been reduced or less severe. We filed suit and sent a demand letter to the insurance company, who settled at mediation with us and provided the funds for the repairs to the exterior of the home as well as a brand new roof for our clients.

Because an insurance company has an obligation of good faith and fairness with the people it insures, those who believe an insurance company has not acted fairly and in good faith also can have a claim for common law bad faith and statutory violations. The Texas Insurance Code also provides the rules for how insurers must behave towards policyholders.

Houston Property Insurance Lawyers

Has your homeowner’s or commercial business insurance claim been denied? We can help. Representing thousands of clients against big insurance companies, our insurance claims attorneys aggressively protect the rights of the policyholder. Our consultations are free, and you owe us nothing until we win your case. Contact us today.

Any-Which-Way-the-Wind-Blows-in-Georgia

Any Which Way the Wind Blows in Georgia

In the path of the storm was our client, a nursing home. Wind-blown debris brought on extensive roof damage along with exterior property damage to the siding, gutters, and HVAC units. This region has a history of property damage going back as far as 1845, so for the residents of the area getting used to property damage has become routine. What is also routine is how our client’s insurer responded to the commercial business insurance claim.

If your commercial business or homeowner insurance claim has been denied then you may be interested in how we have helped this client!

On October 11th, 2018, Hurricane Michael impacted Dougherty County, Georgia. What was the first Category 4 hurricane to hit the US mainland in over a century slowly progressed through Florida into George, where it became a Category 3 by the time it reached the city of Albany. The wind damage was more severe than the damage sustained in Hurricane Irma from a year previous, with wind gusts reaching over speeds of a hundred miles per hour. Many trees had been knocked down along with several businesses losing their facades and an abundance of road debris. The hurricane damage was so bad that residents were asked to stay inside. More than ninety percent of Albany’s Utilities Authority’s customers (24,000+ people) woke up Thursday morning with no power.

Insurance Policies Versus State Laws

Some insurance companies are allowed by the state to have shorter deadlines than the state’s law allows if the parties involved can agree. Georgia’s laws have a general two-year statute of limitations, but per our client’s insurance policy they were only allowed one year to file a lawsuit.

Thirteen days after the one-year limitations period, the insurance company sent our client a claim determination letter stating they had completed their review and determined there was no coverage. Later, we filed suit on behalf of our client. The insurance company responded with a motion to dismiss – claiming we filed suit more than a year after the date of loss. Our response to the court was that we did not have the right to sue until after the determination letter was received by our client and therefore excused from the one-year statute of limitation and the court should disregard the one-year statute of limitations.

On September 30th of this year, the court dismissed the motion to dismiss citing case law, that if the insurance company continues to adjust the claim with the insured and indicates the insurance company is continuing its investigation then the insured is excused from the one-year statute of limitations.

Professional Property Insurance Lawyers

If your commercial business or homeowner insurance claim has been denied, delayed, or underpaid your insurance claim, then we can help. The experienced attorneys at Chad T. Wilson Law Firm have represented more than a thousand clients in cases against insurance companies. Our property insurance lawyers aggressively protect the rights of insurance policyholders. Our consultations are free, and you owe us nothing until your case is won. Contact us today to see how we can help.

Refrigerator Leak Takes Out Kitchen

Refrigerator Leak Takes Out Kitchen

Have you had an appliance leak or flood event in your home and your insurance claim was denied?

For most households, water damage is caused by plumbing or appliance failures. The bills for this type of property damage can add up to hundreds or even thousands of dollars. Historically, only about 8% of interior water damage claims are from weather-related events. Approximately 30% of homeowners insurance claims are caused by appliance failures, while the remaining 62% are often hosing or pipe burst related. The general rule for a water leak or flood event-related homeowners insurance claims is that the insurance policy does cover sudden bursts or breaks in the line causing damage. 

A Damp Evening At Home

On February 4th, 2019 a client of ours was home enjoying her evening when she was suddenly called to the kitchen by the sound of rushing water. The water line for the refrigerator’s icemaker had ruptured and was spewing water everywhere. The water line had to be shut off to stop the rush of water. In the span of a few minutes the kitchen cabinets, flooring, baseboards, and moldings were soaked. In the hours afterward, many of these same materials began to swell from their absorption of water. The leak was so severe that water had made it out of the kitchen area and into the adjacent dining room, warping and distorting the laminate floor as well.

Once the water had begun to dry up, our client reached out to her insurance company, ASI Progressive, and filed a homeowners insurance claim with them. The insurance company responded by sending out an adjuster who was replaced by another adjuster who was replaced (yet again) by another adjuster. This third adjuster concluded the damages to be minimal and directed her to go to her local big-box hardware store and purchase mismatched replacement cabinets, flooring, and molding. The insurance company was offering to pay for half of the mismatched kitchen cabinets.

Dismissed Her Leak Without A Second Thought

Without a functional kitchen and dining room, the expenses really started to add up for our client. The bleak outlook forced our client to hire us to represent her against ASI. Upon hiring us, we uncovered the mishandling of our client’s claim and fought ASI on their gross underpayment of our client’s homeowners insurance claim.

A demand letter from us was written up and mailed to API Progressive. Seeing that our intentions were to go after every last dollar due to our client, the insurance company settled with us, out of court, for 5 times the initial amount offered to our client. With funds in hand, our client was able to make the necessary repairs to her home and now enjoys cooking and entertaining in her home, as she did pre-loss. This case was settled within 45 days of ASI receiving our demand letter.

Texas Property Insurance Lawyers

Has your homeowner’s insurance claim been denied? We can help. Representing thousands of homeowners against big insurance companies, our home insurance claims attorneys aggressively protect the rights of the policyholder. Our consultations are free and you owe us nothing until we win your case. Contact us today.

Homeowner's Insurance Claim Gets Back On Track

Homeowner’s Insurance Claim Gets Back On Track

Have you had storm damage and are now struggling with a homeowner’s insurance claim?

Storm damage hits Mineola, Texas, a small community in Wood County about 80 miles east of Dallas. Mineola is a railroad town and can trace its roots back as far as 1873. With a population just under five-thousand, life in this small Texas town tends to move at a slower pace. Some insurance companies prey on these areas. Such was the case for our clients, whose home was savagely beaten by the hailstorm the night of June 19, 2019 when their home was damaged. The homeowner’s insurance claim was initially denied.

We Will Not Be Railroaded

That night hail pounded Wood County, dropping hail the size of golf balls in some areas. The roof damage to our client’s home was so severe that rainwater had penetrated through the damaged portions of the roof and saturated sheetrock and carpeting throughout the home.

After completing a homeowner’s insurance claim with their insurer, our clients’ claim was denied. Refusing to accept a denial as the outcome, our clients’ pleaded with their insurer. The insurance company in turn sent out an engineer to inspect the roof damage. The engineer’s assessment was that the property damage should be covered under the homeowner’s insurance claim, but the amount of the damage was under the deductible.

Insurance Company Has One Track Mind

Knowing that they were in for a hard fight if they wanted any form of recovery, our clients hired us to represent them. The Chad T. Wilson Law Firm sent our clients’ insurer a demand letter that let the insurer know our client’s were serious about their claim. Upon receiving the demand letter, the insurer reversed course and agreed to pay for the roof and interior damage.

Homeowner’s Insurance Claim Gets Approved

From start to finish, this case was resolved in 30 days. There was no need for mediation or court.

Texas Property Insurance Lawyers

Has your homeowner’s or commercial business insurance claim been denied? We can help. Representing thousands of client’s against big insurance companies, our insurance claims attorneys aggressively protect the rights of the policyholder. Our consultations are free, and you owe us nothing until we win your case. Contact us today.

Tornados-min

State Farm Denies Hailstorm Damage

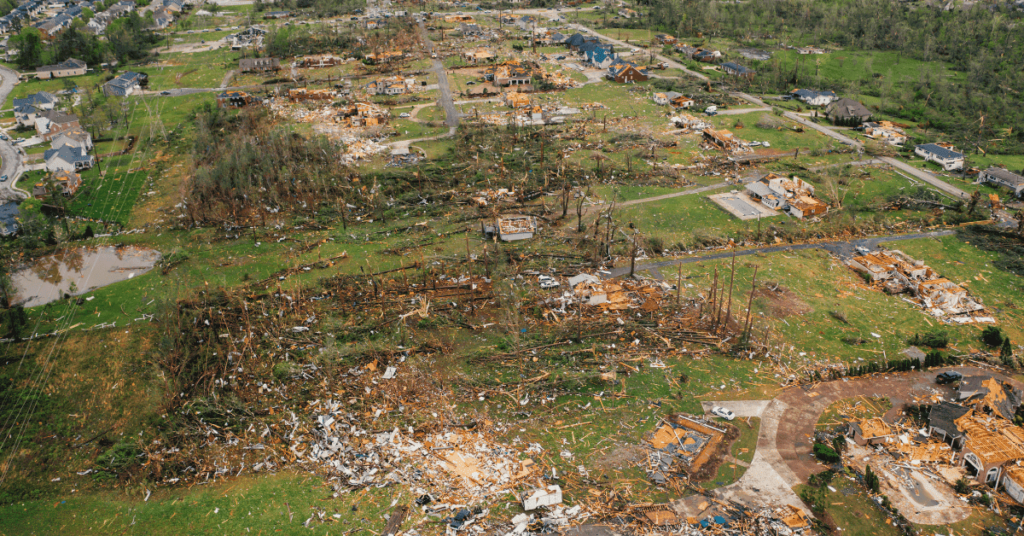
In late April 2015, hailstorms and tornadoes ripped through the southeastern states, leaving behind destroyed homes and damaged lives in their wake. Our client, a woman in Spring, Texas, and her home were no exception.

After the storm, she immediately filed a claim with her homeowner’s insurance company for hailstorm damage, State Farm, asking them to pay for the damages so that she could make repairs and start getting her life back in order.

State Farm hired an adjuster to inspect our client’s home and assess the damage. The inspector found that there were less than $500 worth of damages to our client’s home and found “no hail related damage to shingles,” therefore denying her claim and leaving her with no recovery to make repairs to her home.

So, our client hired a public adjuster, who conducted an unbiased inspection and found a litany of hailstorm damage that State Farm’s adjuster had left off, resulting in more than $44,000 worth of damages to the home. Seeing that she was owed much more than State Farm suggested, the client promptly sought out Chad T. Wilson Law Firm to help her obtain the recovery she had, essentially, already paid for through the purchase of her insurance policy.

On Tuesday, July 5, 2016, the Chad T. Wilson Law Firm filed suit against State Farm insurance company in Harris County, Texas for violations of the Texas Insurance Code and wrongfully denying her coverage under her policy.

Through its adjuster, State Farm conducted a substandard and improper inspection of the client’s home, which grossly undervalued the cost of repairs in its estimate and yielded an unrealistic amount to underpay coverage. State Farm unreasonably adjusted our client’s claim, misrepresenting the cause of, scope of, and cost to repair damages to her property.

Because of State Farm’s misrepresentations, our client was forced to hire an attorney to file a lawsuit for insurance benefits.

If your homeowner’s insurance carrier has denied your insurance claim, we can help. The experienced property insurance attorneys at Chad T. Wilson Law Firm have represented more than 1,000 clients in cases against insurance companies and aggressively protect the rights of insurance policyholders throughout Texas. Our consultations are free, and you owe  us nothing until your case is won. Contact us today to see how we can help.

What-Hailstorm-Litigation-Reform-Means-for-You

Texas Hailstorm Insurance Litigation Reform

Insurance lobbyists are trying harder than ever to convince Texas lawmakers to enact needless hailstorm litigation reform.

In 2015, the Texas legislature nearly passed a bill that would have incentivized insurance companies to underpay claims. In February of this year, Gov. Abbott called hailstorm litigation a crisis that needed to be reined in. Now, insurance companies are hard at work informing lawmakers of the injustices of attorneys fighting for their clients.

State Farm Lobbies to Dismantle Policyholder Rights

In State Farm’s most recent papering of Texas congressmen’s and congresswomen’s offices, the insurance giant asserted that policyholders should accept whatever decision the company came to regarding claims, and not sue. “The Texas Legislature should move quickly to encourage the quick and fair settlement of insurance claims  following severe weather events while protecting the interests of Texas policyholders and discouraging the filing of frivolous insurance lawsuits.”

We’re all for the quick and fair settlement of claims, but we think State Farm’s definition is quite skewed. The 2015 proposed bill tried to undo 40 years of protections that ensure insurance companies are fair. In the proposed changes, policyholders would barely have time to file claims after an storm. Insurance companies would be encouraged to deny claims. And fraud and negligence would go unchecked and unpunished.

To us, the best way to protect the interests of policyholders is to pay them the insurance money they deserve in the first place. But, companies like State Farm are slanting the narrative in their favor.

They’ve convinced the governor of Texas that policyholders suing for their rights is “the newest form of lawsuit abuse.” Abbott said in his January state of the state address that he would like to see on his desk legislation “that limits abusive hailstorm litigation.” With proposed policies that would allow insurers to abuse the system, the irony isn’t lost on us.

Proponents of the law suggested policy changes chalk the justification up to decrying a small number of “storm-chasing” attorneys that prey on victimized policyholders. Consumer advocates, however, point out that the changes paint with too broad a brush and would prevent policyholders from holding insurance companies accountable for errors and perceived wrongdoing in the claims handling process.

The Truth About Hailstorm Litigation Reform

At a Dec. 1, 2016 House of Representatives insurance committee hearing, a representative of the Office of Public Insurance Counsel (OPIC), Joe Matetich, told lawmakers that a “statewide hail litigation crisis does not currently exist in Texas,” and that there “does not appear to be an insurance market problem” in Texas. Matetich gathered his information from research that lawmakers requested the Texas Department of Insurance conduct.

Ware Wendell, a representative of Texas Watch, testified that there are already “laws on the books that protect insurance companies, agencies, and adjusters. Many of these laws came from tort reform back in 1995.” Wendell continued to explain that Texas Watch is concerned that, if the insurance industry succeeds in limiting policyholders’ access to lawsuits, the scales will tip “further in favor of the insurance companies.”

Matetich’s and Wendell’s testimonies certify that insurance companies are using scare tactics and made-up “facts” to persuade lawmakers to keep you, the policyholder, from holding them accountable. They’re trying to make sure that, if they deny or underpay your claim — which the reform would incentivize them to do — there is nothing you can do to fight back.

Take Action

So, what can you do to protect yourself and ensure insurance companies are held accountable for their fraud and gross negligence?

  1. Educate yourself. Learn more about the lobbyists tactics and 2015’s proposed bill here, and research hailstorm litigation reform from reputable sources. (Try your local paper or any major Texas news outlets.)
  2. Call or email your state senator to voice your concerns and give your testimony to be included in the meeting records.
  3. Find a special interest group that will represent you through formal letters, petitions and testimony.
  4. Get a great lawyer. The experienced attorneys at Chad T. Wilson Law Firm fight for our clients’ rights every single day. We’ve represented more than 1,000 homeowners throughout Harris County and East Texas to get them the insurance payments they rightfully deserve.
North-Dallas-Sees-Softball-Sized-Hail

North Dallas Sees Softball-sized Hail

Softball-sized Hail Hits North Dallas

Nestled on the south side of the western edge of Lewisville Lake rests the City of Highland Village. This suburb of north Dallas is known for its annual hot air balloon festival and its summertime firework shows. The region is also known for its history of wind damage and hailstorms.

Softball-sized Hail Thrashes Denton County Costing Millions

On Sunday night, March 26, 2017, a powerful hailstorm (fueled by an abnormal amount of moisture from the Gulf of Mexico) blew through wreaking havoc as it passed through. Softball-sized Hail measured up to four and a half inches across was witnessed by residents. For comparison, a softball is four and a quarter inches across. Thousands of property owners reported severe roof damage, along with busted-out skylights and windows. The majority of the property damage occurred in fifteen minutes after 8 p.m. that night. The hailstorm was reported to be so bad, one Fire Chief’s windshield was destroyed and he had to leave his vehicle and take shelter in an abandoned building for protection.

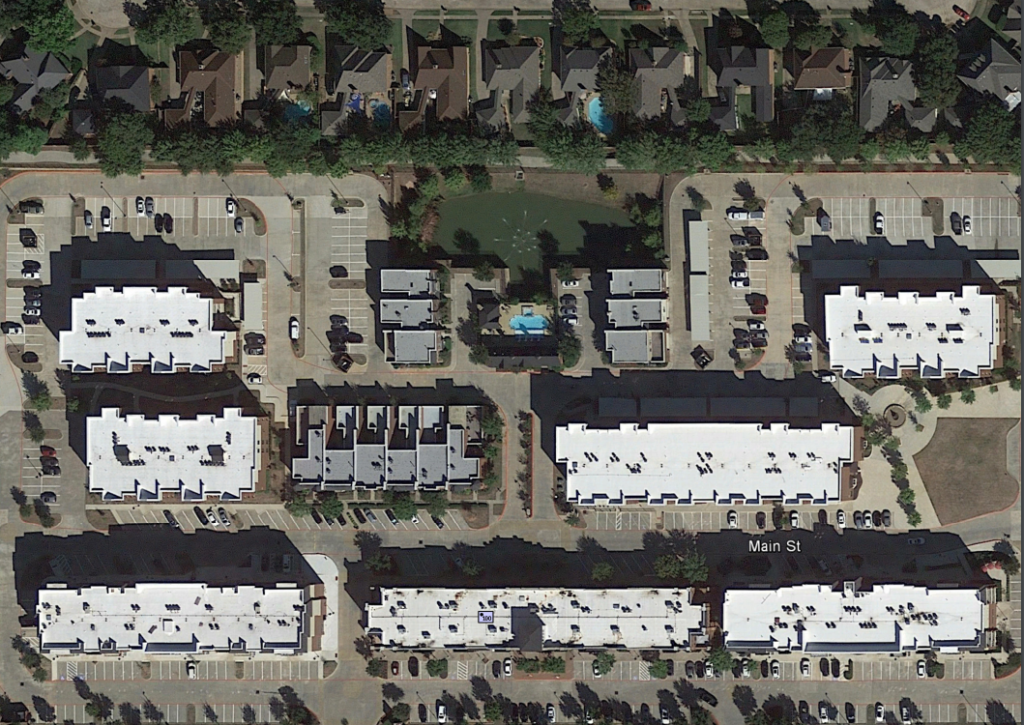
Our client’s newly constructed, multi-use commercial complex (or town center), which consisted of shops, stores, a leasing office, and apartments experienced the full force of the hailstorm. A total of eleven roofs (4 TPO, 3 modified bitumen, 2 three-tab shingle, and 2 laminated composition shingle), and all the roof-mounted HVAC equipment and accessories were damaged beyond repair or destroyed. The fact that these new roofs had to be replaced is a testament to the property damage that occurred.

Quadrupling The Award Is The Reward

AmGuard Insurance responded to our client’s insurance claim by sending out their adjustors who substantially undervalued the damage. Knowing AmGuard’s inspection results did not represent reality, our client hired us to represent them against their insurance carrier.  After our representation concluded, our client had ample funds to replace all eleven damaged roofs and acquire new HVAC equipment for the complex as well as reimburse litigation expenses and pay the firm’s fee.

Texas Property Insurance Lawyers

Has your homeowner’s or commercial business insurance claim been denied? We can help. Representing thousands of client’s against big insurance companies, our insurance claims attorneys aggressively protect the rights of the policyholder. Our consultations are free, and you owe us nothing until we win your case. Contact us today.

1 7 8 9 10 11 13