On September 19th, we celebrate International Talk Like a Pirate Day—a fun reminder of the days when treasure, ships, and the high seas ruled the world. But did you know that modern property insurance can trace its roots back to the dangerous days of piracy?

Early Beginnings: Hammurabi 

The early days of insurance were born out of necessity on treacherous waters. The origins of insurance can be traced back to ancient Babylonian times, as early as 1750 B.C.! 

The concept of insurance emerged through the Babylonian practice of bottomry, introduced in the Code of Hammurabi. An early form of insurance, bottomry allowed merchants to secure loans against their ship’s cargo. 

To limit their risks, goods would be divided among several ships. This way, even if one vessel fell victim to marauding pirates, the entire shipment wouldn’t be lost. If the cargo was lost at sea—due to piracy or natural disasters—the loan did not have to be repaid. This practice highlighted the need to spread risk across multiple parties to minimize individual loss.

History of insurance Pirates and Property Insurance a cartoon of a ship in the ocean during Ancient Babylon

Medieval Guilds and Group Coverage

In medieval Europe, the guild system offered a different kind of insurance, focusing on craftsmen and their livelihoods. Guild members would pool resources to protect against losses such as theft, fire, or even death. This communal approach to risk management allowed more people to leave farming for trades– ultimately contributing to economic diversification and growth.

a cartoon of a boat in the water

The Role of Lloyd’s of London

As European powers expanded their trade routes to the New World in the 1600s, the high seas became rife with pirates who targeted ships carrying valuable goods such as gold, silver, spices, and tobacco. The risk of losing an entire shipment to pirates was still very much a reality, and this spurred the development of more sophisticated insurance practices.

Lloyd’s of London, originally a humble coffeehouse, became a meeting spot for merchants and shipowners to secure maritime insurance. 

At Lloyd’s, shipowners, merchants, and investors would gather to assess the risks associated with various voyages. They would “underwrite” a portion of the ship’s cargo, meaning they would agree to cover a certain percentage of the losses if the ship were attacked by pirates or succumbed to other dangers. This system allowed merchants to distribute the risk of piracy across multiple investors, making long-distance trade more viable. Thus, the practice of underwriting emerged—shipowners could share the risk with multiple investors, reducing the financial blow of piracy.

It was because of this that Lloyd’s of London became a hub for maritime insurance, particularly in an era when piracy was a constant threat. The ability to spread risk through multiple underwriters not only mitigated the financial impact of piracy but also encouraged the growth of international trade.

Pirate Day Pirate Attack on Property Insurance Ship

The Golden Age of Piracy and Insurance Innovation

Considered the Golden Age of Piracy, the 1650s to the 1730s was a period when pirate attacks reached their peak, particularly in the Caribbean. This era saw the emergence of famous pirates like Blackbeard and Captain Kidd, whose exploits terrorized merchants and shipowners. The high frequency of pirate attacks led to increased demand for insurance, as merchants sought to protect their investments.

Insurance companies responded by creating specialized policies that addressed the unique risks posed by piracy. These policies often included higher premiums and more stringent terms, reflecting the heightened danger of maritime trade during this period. The development of these policies marked a significant advancement in the insurance industry, as insurers began to differentiate between various types of risks and tailor their offerings accordingly.

Legal and Military Responses to Piracy

Governments increased naval patrols and enacted harsh penalties for piracy. However, pirates adapted and endured during this time as well, never making it easy for governments or companies to predict their next move.

The War of Jenkins’ Ear (1739–1748) between Britain and Spain saw a significant increase in piracy, leading to higher insurance premiums for merchants. In response, insurance companies developed more sophisticated methods of risk assessment and began offering policies that specifically covered losses due to piracy.

The Decline of Piracy and the Rise of Modern Insurance

By the mid-18th century, piracy began to decline due to increased naval presence and international cooperation against pirate activities. As the threat of piracy diminished, insurance companies shifted their focus to other emerging risks, such as natural disasters and war. However, the legacy of piracy continued to influence the insurance industry, particularly in the areas of risk assessment and underwriting practices.

The decline of piracy also coincided with the growth of the global insurance market, as companies expanded their offerings to cover a wider range of risks. The principles established during the era of piracy—such as spreading risk and tailoring policies to specific threats—became foundational elements of modern insurance practices.

Ahoy!

The history of insurance is a story of adaptation to ever-present risks, with piracy playing a crucial role in shaping the industry. From the early days of bottomry in ancient Babylon to the sophisticated underwriting practices at Lloyd’s of London, the need to manage the threat of piracy drove significant innovations in insurance. Insurance has evolved from these early maritime practices to become the industry it is today. While they once were for the little guy, it seems today, many insurance companies ARE the pirates. Whether you’re protecting your treasure chest or your home, insurance should ALWAYS have your back!


In a significant move affecting Texas homeowners, Progressive Insurance has announced a temporary suspension of offering new homeowners insurance policies in the state. This decision comes on the heels of Hurricane Beryl’s devastation across Houston and raises concerns about the stability of the homeowners insurance market in Texas.

At Chad T. Wilson Law Firm, we understand the challenges that homeowners face when navigating insurance claims, especially during times of crisis. This article aims to provide a comprehensive overview of the situation and offer guidance to those affected.

Progressive’s Decision and Its Implications

Temporary Restriction on New Policies

In a recent letter to shareholders, Progressive Insurance CEO Tricia Griffith stated that the company is “temporarily restricting new homeowners’ business” in Texas. The move is part of a strategic effort to reduce the impact of weather-related volatility on the company’s portfolio.

Focus on Weather-Related Risks

Griffith emphasized the importance of shifting the company’s geographic mix, focusing on growing in states with lower weather risks while reducing exposure in areas more susceptible to catastrophic events like hurricanes and hailstorms.

Impact on Existing Policyholders

While the suspension currently affects new policies, there is concern among existing policyholders about potential non-renewals or premium increases. In Florida, Progressive previously dropped 115,000 policyholders due to similar concerns over natural disasters.

Wind Damage Claims Lawyer

Rising Insurance Costs for Texas Homeowners

Homeowners across Texas are experiencing significant hikes in insurance premiums. Some residents have reported increases from $2,600 to $8,800 within a year, making it increasingly difficult to maintain adequate coverage.

Comparison with National Averages

According to Bankrate, Texas homeowners pay an average of $3,898 for $300,000 in dwelling coverage—72% more than the national average of $2,270. These escalating costs highlight the growing financial strain on Texas residents.

What Is an Insurance Appraiser and What Do They Do?

Other Insurers Following Suit

Progressive is not alone in this trend. Foremost Insurance, a subsidiary of Farmers Insurance, ceased writing and renewing new policies shortly before Hurricane Beryl struck. In communications to customers, the company cited a reassessment of risks related to natural and catastrophic losses.

Potential for a Widening Crisis

The withdrawal of major insurers from the Texas market could exacerbate the homeowners insurance crisis, limiting options for residents and potentially leading to higher rates due to decreased competition.

tornado damaged house with a blue tarpaulin on the roof

Options for Texas Homeowners

Texas Fair Plan Association

For those struggling to obtain coverage, the Texas Fair Plan Association (TFPA) offers a lifeline. Established by the Texas Legislature in 1995, TFPA provides basic property insurance for eligible Texas homeowners who are unable to secure coverage through the voluntary market.

Considerations

While TFPA can be a valuable resource, policies may come with limitations and higher premiums. Homeowners should carefully assess their coverage needs and explore all available options.

Insurance Adjusters

Legal Recourse and Support

Understanding Your Rights

If your insurance policy has been non-renewed or you are facing exorbitant premium increases, it’s crucial to understand your legal rights. Insurance companies are obligated to follow state regulations when making such decisions.

How Chad T. Wilson Law Firm Can Help

Our firm specializes in representing policyholders in disputes with insurance companies. We offer:

  • Free Consultation: Assess your situation with no obligation.
  • Expert Representation: Navigate the complexities of insurance law with seasoned professionals.
  • Contingency Basis: No fees unless we secure a recovery on your behalf.

Steps to Take if Affected

  1. Review Your Current Policy: Understand the terms, coverage limits, and any notices of changes or non-renewal.
  2. Explore Alternative Insurance Options: Seek quotes from other reputable insurers still operating in Texas.
  3. Consult with an Attorney: If you believe your rights are being infringed upon, legal advice can provide clarity and direction.
  4. Stay Informed: Monitor communications from your insurer and stay updated on industry developments.

Conclusion

The decision by Progressive Insurance to halt new homeowners policies in Texas underscores the challenges facing the state’s insurance market. As natural disasters become more frequent and severe, homeowners must be proactive in securing adequate coverage and advocating for their rights.

At Chad T. Wilson Law Firm, we are committed to assisting Texas homeowners during these uncertain times. If you have concerns about your insurance coverage or need legal assistance, please reach out to us.

Contact Us Today

Stay Protected. Stay Informed. We’re Here to Help.


Tips for 2024 Derecho and Hurricane Beryl Storm Claims


Texas residents and property owners continue to be absorbed in the post-derecho of 2024, and Hurricane Beryl. Navigating the storm of insurance claims can be maddening and confusing. But that’s not surprising when your house or business is damaged or destroyed and you are dealing with property damage and loss. Here’s a brief blog to address the concerns that most Texas citizens will have after going through a tumultuous time and dealing with an insurer or insurers on a claim.

Reviewing Policy for Derecho and Beryl Claims

Whether you have suffered a home covered by your insurance or not, the first thing you want to do with your insurance company is to read – or better yet, have an attorney read – your policy. This is the document that spells out what is and is not covered in the event of windstorms, hail damage, flood damage and other natural disasters that are often a part of a derecho and a hurricane.

  • Make sure there’s no exclusion on the policy for the things you care about – for example, water damage from certain types of plumbing problems or mold.
  • You Live in the Family Home: Did you know that, for a fire-related claim, you must stay in the home and ensure it is habitable? Know Your Deductibles: Did you know that you have to pay deductibles out of pocket before insurance starts paying your claims?

Common Reasons for Claim Delays and Denials

There why an insurance claim might be delayed or denied – none of them absolute nightmare scenarios, but all of them worth knowing about so you can avoid the common traps.

  • Incomplete Documentation:

    One of the most significant causes for delays is incomplete documentation.
    • Submit all required forms and evidence promptly.
    • Keep detailed records, including photos and receipts.
  • Policy Exclusions:

    Policies often contain specific exclusions that can complicate claims.
    • Carefully read the exclusions section to understand what is not covered.
    • Consult with an attorney if you have concerns about the language of your policy.

Handling Disputes with Your Insurance Company

Unfortunately, disagreements over benefits are not uncommon between policyholders and insurers, especially after a widespread disaster has occurred. Here are some things you can do if you find yourself in a dispute.

  • Always request detailed explanations for any denials or reductions of your claim.
  • Ask for an Unbiased Review: Hire an independent appraiser to come in and review what was broken and objectively describe what was damaged.
  • Keep a Timeline: Keep a meticulous timeline of all your interactions and communications with your insurance company.
  • Document Everything: Writing is better than talking, if you get the message in writing.

Legal Recourse

And if everything else fails, filing a lawsuit may be your last resort. The Chad T. Wilson Law Firm represents policyholders in this regard.

When to Contact an Attorney

It’s not easy to know when to contact an attorney, but typically if your claim is significantly delayed, if you are wrongly denied, or if settlements are extremely low, you should consider hiring an attorney.

  • Prolonged Delays:

    If your claim is delayed without reasonable cause.
  • Unfair Denials:

    If you believe your claim has been unjustly denied.

How We Can Help

Our firm, the Chad T Wilson Law Firm, helps policyholders recover the full measure of their recoverable benefits. We are skilled insurance policy specialists and work to make sure you receive the benefits you are owed.

  • Free Consultation:

    We offer a free consultation to evaluate your case.
  • Contingency Basis:

    based on contingency fees – you don’t pay unless we recover a settlement on your behalf.

Steps to Strengthen Your Claim

Here are some things you can do to prepare yourself well in advance to make a stronger case:

  • Photograph Everything:

    Take multiple photographs of the damage from various angles.
  • Secure Temporary Repairs:

    If possible, secure temporary repairs to prevent further damage.
  • Collect Receipts:

    Obtain receipts for temporary repairs and lodging if you need to leave your home.
  • Keep All Communications:

    Save every email, letter, and note related to your claim.
  • Create a Claim Diary:

    A diary keeping track of every step you take and every person you contact can be useful.

Conclusion

Despite the trauma of surviving the 2024 derecho and Hurricane Beryl (and the aftermath of the record-breaking insurance claims), you don’t have to feel that you’re back in the deep end. You can educate yourself about your policy; know what kinds of claims are most commonly denied; and, when needed, work with an attorney.

The Chad T Wilson Law Firm is dedicated to helping Texans rebuild and recover through these trying times. If you find yourself in a fight with your insurance company over a claim, call us today for a free consultation and let us help you get the compensation you deserve.

Learn more about us at cwilsonlaw.com or call 833-942-0678 to schedule a consultation.

Insurance Attorney Can Be Your Beacon After Texas Storms

In the wake of the devastating storms that swept through Texas, countless residents are now embarking on the challenging journey of recovery. This path is often complicated by the daunting task of navigating insurance claims, particularly when faced with denials or underpayments by insurance companies. This is where the Chad T. Wilson Law Firm emerges as your advocate and guide, ensuring that you traverse these complex legal pathways with confidence and obtain the compensation you rightfully deserve.

Our firm is anchored by a formidable team of dedicated property insurance attorneys, who specialize in the nuances of storm damage claims, including Texas windstorm and hail damage. The Chad T. Wilson Law Firm operates on the foundational belief that justice for policyholders should be unwavering and pursued with tenacity. Our legal expertise encompasses a broad spectrum of storm-related damages, highlighting our role as a leading hail damage claim and wind damage attorney. We stand as a beacon of hope and unwavering support for Texans who find themselves at the mercy of an insurance system that too often seeks to minimize payouts rather than alleviate loss.

Why You Need a Champion in Your Corner

Our firm has consistently observed countless instances where insurance companies, under the guise of complex policies and provisions, deny or undervalue legitimate claims. This practice, unfortunately common, leaves policyholders stranded. The aftermath of the Texas storms has vividly illustrated this issue, with innumerable families and businesses discovering their pathways to recovery unjustly obstructed by insurance denials.

The necessity of engaging a storm damage lawyer in these situations is paramount. The Chad T. Wilson Law Firm not only provides you with stalwart legal representation but a team deeply familiar with both the Texas environment and the unique challenges posed post-storm. Our attorneys excel at unraveling the complex language of insurance policies and identifying key elements that can transform a denied hail damage claim into a successful recovery, all within the hail damage claim time limit.

Your Recovery is Our Priority

Our strategy is rooted in thorough analysis and assertive representation. When we take on your case, it becomes a mission. We meticulously assess the damages, carefully review your insurance policy’s terms, and craft a strong case aimed at securing your rightful compensation. Our considerable success stories echo our legal prowess and steadfast commitment to our clients’ welfare.

The Chad T. Wilson Law Firm works on a contingency basis, affirming our confidence in our ability to deliver results. This means you incur no out-of-pocket expenses; our compensation is tied to the successful outcome of your case. In essence, our interests align perfectly with yours — securing the maximum recovery for your storm-related losses.

Empowerment through Legal Advocacy

At the core of our practice is empowerment. By lifting the legal burden from your shoulders, we enable you to focus on rebuilding, knowing your claim is managed by experienced professionals. Our team diligently navigates legal complexities, liaises with insurance companies on your behalf, and fights for the compensation you legally deserve.

The unpredictable Texas weather can wreak havoc, leaving behind a path of destruction. Yet, the journey to secure a fair insurance settlement in the wake of such events should not exacerbate your stress. With the Chad T. Wilson Law Firm at your side, representing you as your trusted wind damage attorney and storm damage lawyer, you’ve secured a formidable ally against the injustices of the insurance claims process.

The Path Forward

Recovery from the Texas storms is a daunting challenge. However, with the Chad T. Wilson Law Firm by your side, you have an empowered ally to guide you through the chaos that follows. We invite you to take advantage of our expertise, compassion, and relentless pursuit of justice for Texas policyholders.

The journey to recovery is undoubtedly filled with hurdles, but it’s a journey you don’t have to make alone. Contact us for a free consultation — let’s explore how our dedicated team can help you reclaim your peace of mind and secure the compensation necessary for rebuilding. In the face of a storm’s aftermath, remember, you have rights. Let Chad T. Wilson Law Firm be your voice.

Is your claim being denied or underpaid? Call Chad T. Wilson Law Firm, PLLC.

Speak with one of our attorney if you’re having trouble getting your claim processed or if the insurance company is attempting to pay less for the claim than is reasonable.

Contact us: https://cwilsonlaw.com/contact-us/ 

Follow us on Social media: https://beacons.ai/chadtwilsonlaw

Contact our office locations to schedule a free consultation.


Chad T. Wilson is an attorney whose firm specializes in property insurance disputes.

Schedule a free Consultation

Chad T. Wilson – What Is the Difference Between RCV and ACV Coverage? (2024)
April 25th, 2024
Source: https://cwilsonlaw.com/
https://www.opic.texas.gov/residential-property-insurance/basics/acv-vs-rcv/

So what is the difference between RCV (replacement cost value) insurance and ACV (actual cash value) insurance?

What is RCV and ACV?

If you have replacement costs or RCV coverage, your insurance policy will pay the cost to repair or replace your damaged property without deducting depreciation.

If you have actual cash value or ACV coverage, your insurance policy will pay the depreciation costs to repair or replace your damaged property.

Regardless of what type of policy you have, the company will first pay you the ACV of an item, which means depreciation will be withheld.

If your policy allows RCV coverage, once the property is replaced, they will release the deductible depreciation, giving you the full replacement cost of your policy. If you upgrade your policy, the difference will be your financial responsibility as the insurance company will not allow the upgrade.

All additional estimates must be submitted to your insurance company for approval. If you’re not sure what type of coverage you have, check the declarations page of your home insurance policy to see if it offers replacement cost coverage.

If it specifies a replacement cost, then you will benefit from replacement cost coverage. If it doesn’t specify a replacement cost, your policy likely only covers actual cash value. Remember that there are different ways for your insurance company to handle your claim, depending on the type of insurance policy you have.

RCV (Replacement Cost Value)

Replacement cost settlement ensures that you receive compensation equivalent to the current market value needed to replace a damaged item. Let’s consider the case of replacing a 10-year-old roof, which is estimated to cost $30,000. With a deductible of $1,500 and a recoverable depreciation of $15,000, the insurance company initially provides an Actual Cash Value (ACV) payment of $13,500. Upon completing all necessary repairs, you become eligible to claim the remaining $15,000 in recoverable depreciation. 

This means you can potentially recover up to $28,500 after all claim payments have been processed, ultimately covering just your deductible. The insurance payout calculation involves deducting the recoverable depreciation and deductible from the cost of the new roof, resulting in an initial payment of $13,500. Subsequently, once repairs are finalized, you can claim the remaining $15,000 in recoverable depreciation, leading to a total insurance claim settlement of $28,500 after all adjustments have been made.

ACV (Actual Cash Value)

Now, let’s consider a scenario where we compare the insurance settlement approaches. An Actual Cash Value (ACV) settlement allows the insurer to compensate you for the cost of repairing or replacing your property, minus depreciation. Depreciation, representing the decline in asset value over time due to age or usage, is calculated at $1,000 per year. For instance, if the cost to replace a 10-year-old roof is $30,000, with a deductible of $1,500 and an irrecoverable depreciation of $15,000, the ACV payment from the company would amount to $18,500.

Under your insurance policy, your out-of-pocket expense will be limited to your deductible amount. In the case of a Replacement Cost Value (RCV) policy, you might also need to cover the recoverable depreciation. Keep in mind that the insurance company won’t automatically reimburse you for recoverable depreciation; you’ll need to provide supporting documentation, like paid receipts for repairs and relevant photos. You’ll have a specific timeframe to submit these documents for the company to consider releasing any recoverable refund funds.

The insurance payment is calculated by taking the cost of the new roof, which is $30,000. Next, you subtract the depreciation, which is $1,000 per year over 10 years, giving you a total depreciation of $10,000. Then, subtract the deductible of $1,500. This results in a total insurance payment of $18,500.

You will be responsible for your deductible and the remainder of the difference. As evident, the same damage can yield varying insurance payments. While an Actual Cash Value (ACV) policy typically offers lower premiums compared to Replacement Cost Value (RCV) policies, the latter aims to fully compensate the policyholder for covered losses. Understanding your policy and selecting the most suitable option is crucial. For any additional questions or concerns, it’s advisable to contact your insurance agent or company.

Take Your Time When Purchasing Property Insurance
Why It’s Important To Take Your Time When Purchasing Property Insurance

When you see a doctor, you expect that they will take their time to do their job and understand the need for your visit. When investing money in a business opportunity, you would want to review all available information to make the best decision for your money. The same may be said when taking your car into the shop. When purchasing a service, the reason for your visit is more important than how fast you get the service. Learn how to make your property insurance purchase a smooth transaction.

More insurance carriers are making it easier for first-time homeowners to get home insurance. Obtaining property insurance expeditiously is important. Larger insurance companies can move quickly when it comes to purchasing insurance and smaller insurance companies are following the trend. What is the best insurance and what can you do to avoid making a mistake when purchasing it?

Choosing the Right Coverage

The most important thing in any business is to provide excellent customer service. This includes ensuring that the policyholder has all necessary coverages and not just encouraging them with products they will never use or be able to afford.

When an insurance provider rushes through the purchasing process without thoroughly understanding their customer’s needs, they’re harming not only themselves but also other parties involved in this transaction. By focusing on profits instead of getting to know your clientele and what coverages are needed for them – you hurt everyone who has been relying upon these policies!

A company should never sacrifice its morals just because it wants more customers or greater profit margins; doing so will only come back around at some point anyway with negative consequences that could’ve easily been avoided by taking care beforehand.

Homeowner’s insurance or any type of insurance for that matter is a serious subject. Inadequate coverage can result in financial catastrophe. Insurance companies are in the business of making money, they cannot increase their profits if they roll over and pay every insurance claim. Viewing insurance as a simple means to make money is wrong. People need insurance. People need to be protected.

Choosing the right coverage goes hand in hand with finding the right agent for you and your needs. Insurance can be a confusing topic for the average person, but there are ways to find affordable coverage. Your agent is someone you should contact if anything happens with your policy – they’re in the know and will help make sure that nothing gets left uncovered or unpaid!

Filing a Claim

When filing a claim, customers want to know that their insurer will be able to provide tangible evidence of coverage. We need this assurance before putting any money at risk and without it, we feel uncertain about what kind or how much help is available for an event that has occurred while using their product/service.

If you do not have the right insurance, you could find yourself in a significant financial hole. A thoughtful conversation with an insurance agent can help you avoid these errors.

Take Your Time to Find the Right Agent

Good Insurance agents often face a challenging environment where they must balance the needs of their customers with those companies. Insurance leaders who put profit ahead of customer service will struggle in this competitive market, as knowledgeable and trustworthy professionals like insurance brokers can provide better quality products for clients.

Insurance agents are often expected to spend very little time with their customers, but the best ones understand that every second counts. They know it’s not just about making sales or finding new clients; they need customer input and guidance so insurance products can be tailored specifically for them – which is why we find this situation ironic!

The bottom line is you need to take this important purchase seriously and find an agent that takes the time to find YOU out what you need.

If your property insurance claim has been denied, delayed, or underpaid, contact the expert insurance attorneys with the Chad T. Wilson Law Firm at (833)942-0678 or email us at [email protected].

Screen-Shot-2021-12-29-at-8.38.09-AM-1200x672-min

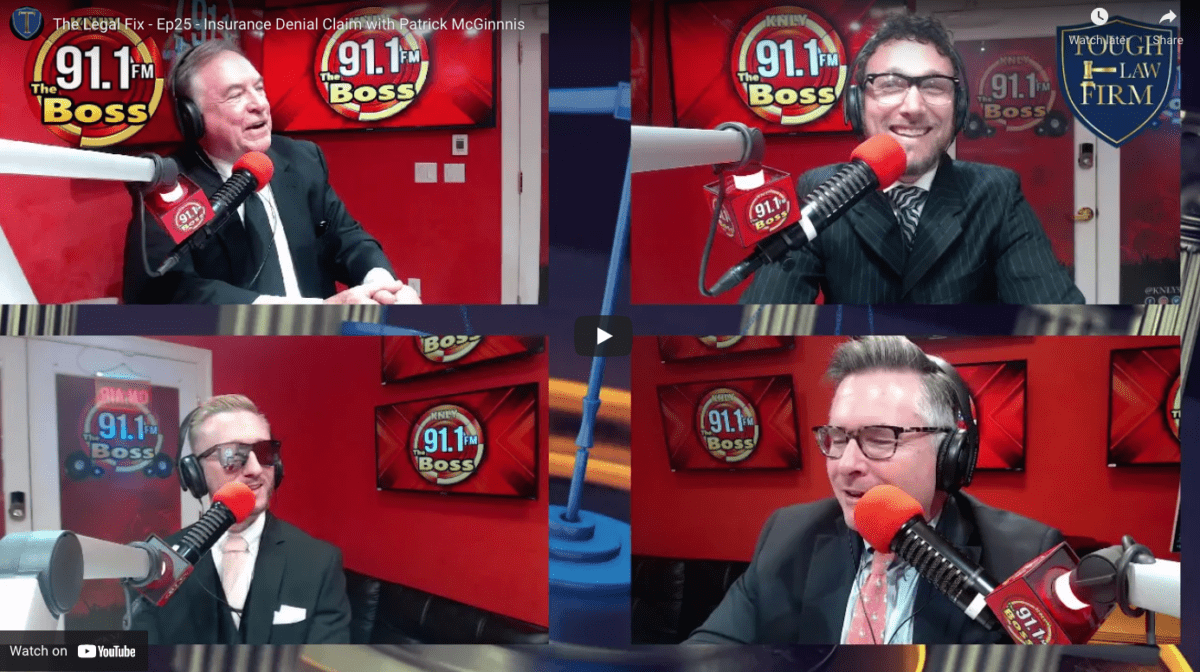
Attorney Patrick McGinnis Talks Winning Claims On ‘The Legal Fix’ Radio Show

Chad T. Wilson Law Firm Attorney, Patrick McGinnis, was a special guest on The Legal Fix radio show last month where he talked about winning denied insurance claims. Has your insurance company unfairly denied your property damage claim? If so, contact us today for a free case review. You may be entitled to compensation.

Houston-Lawyers-Sue-Liberty-Insurance-min

Houston Lawyers Sue Liberty Insurance

Our client, a woman whose home was damaged in a severe storm, recently filed a lawsuit against Liberty Insurance Corporation and its adjuster. Liberty conducted a substandard and improper inspection of our client’s property. They grossly undervalued the cost of repairs and deliberately yielded an unrealistic amount to underpay coverage.

April 27, 2016 Storm

On April 27, 2016, a wind and hailstorm blew through Harris County, tearing through neighborhoods as it went. Our client’s Houston home sustained extensive damage to the exterior, as well as to the electrical and air conditioning systems. After the storm, she promptly submitted a claim to Liberty, hoping her insurance company would help her repair her home.

Liberty Insurance Corporation Home Insurance Claim

Liberty assigned one of its adjusters to inspect the property and adjust the claim. The adjuster knowingly conducted a subpar investigation, refusing coverage. This left our client with zero recovery necessary to make repairs to her home.

The third-party expert hired after the insurance company’s negligent inspection found a litany of damages that Liberty’s adjuster conveniently left out or undervalued in his estimate.

The third party adjuster estimated the real damage to our client’s home at $28,000.

Liberty’s adjuster intentionally undervalued our client’s claims in order to maintain his job. He misrepresented the amount of damage, hoping our client would simply rely on his expertise and fraudulent estimate as a true representation of the property’s damages.

Liberty Insurance Corporation’s fraud forced our client to retain an attorney, just so she could get her roof repaired. On January 16, 2017, the Chad T. Wilson Law Firm filed suit, on behalf of our client, against Liberty Insurance Corporation. The firm is suing for fraud, breach of contract, gross negligence, and violations of the Texas Insurance Code and the Texas DTPA.

Houston Property Insurance Lawyers

If your homeowner insurance carrier has denied your insurance claim, we can help. The experienced property insurance attorneys at Chad T. Wilson Law Firm have represented more than 1,000 clients in cases against insurance companies and aggressively protect the rights of insurance policyholders. Our consultations are free, and you owe us nothing until we win your case. Contact us today to see how we can help.

Auto-Owners-Insurance-Shortchanges-Colorado-Liquor-Store-min

Our client, a liquor store in Colorado, was recently forced to file a lawsuit against Auto-Owners Insurance Company and its adjusters. The store suffered extensive damages when a severe storm passed through Highlands Ranch, Colorado in September 2014. After the hail had passed, our client found themselves in a storm of Auto-Owner’s fraud and deceit.

September 29, 2014 Storm

On September 29, 2014, a severe wind and hailstorm bombarded Douglas County, Colorado, tearing through neighborhoods and destroying homes and businesses as it went. Our client became one of the storm’s many victims when the torrential hail damaged the property. After the storm, the store submitted a claim to Auto-Owners, hoping it would help it get back in business.

Auto-Owners Insurance Company Property Insurance Claim

Auto-Owners hired Monaco Adjusters, which then assigned an agent to adjust the claim. The adjusters estimated the damages to be around $31,000.

But, after applying depreciation and the policy deductible, the store received $13,300. Damages to the liquor store are currently estimated at more than $577,000. They received less than 3 percent of what they were owed based on their policy.

Due to Auto-Owners’s breach of contract, our client was unable to complete any meaningful repairs to the building. They were forced to retain an attorney to pursue their claim for insurance benefits. On September 29, 2016, the Chad T. Wilson Law Firm filed suit, on behalf of our client, against Auto-Owners Insurance Company for breach of contract, bad faith breach of insurance contract, and statuary bad faith.

Colorado Property Insurance Lawyers

If your homeowner insurance carrier has denied your insurance claim, we can help. The experienced property insurance attorneys at Chad T. Wilson Law Firm have represented more than 1,000 clients in cases against insurance companies and aggressively protect the rights of insurance policyholders. Our consultations are free, and you owe us nothing until your case is won. Contact us today to see how we can help.

Dallas-Apartment-Complex-Sues-Scottsdale-Insurance-Company-for-Incompetence-min

Dallas Apartment Complex Sues Scottsdale Insurance Company for Incompetence

Our client, an apartment complex, was recently forced to file a lawsuit against Scottsdale Insurance Company and its adjusters. The complex suffered extensive damages when a severe storm passed through Dallas, Texas in March 2013. After the hail had passed, our client found themselves in a storm of Scottsdale’s fraud and deceit.

March 9, 2013 Storm

On March 9, 2013, a severe wind and hailstorm bombarded Dallas County, Texas, tearing through neighborhoods and destroying homes as it went. Our client became one of the storm’s many victims when every roof in the complex was damaged. After the storm, the complex submitted a claim to Scottsdale, hoping it would help take care of its residents’ homes.

Scottsdale Insurance Company Property Insurance Claim

Scottsdale hired Wardlaw Claims Service LLC, which then assigned an agent to adjust the claim. The adjusters estimated the damages to be around $240,000 and authorized the replacement of all nine of the property’s roofs.

But, when it came time to apply the deductible, Scottsdale got caught double dipping. According to the complex’s policy, the deductible for the claim would be $57,572. According to the adjusters, who either negligently or deliberately misconstrued the policy, the deductible would be $25,000 per building, for a $225,000 total deductible.

Because of Wardlaw’s and its agent’s incompetence, our client was paid only 16 percent of what they were owed.

Due to Scottsdale’s fraud, our client was unable to complete any meaningful repairs to the apartment buildings. They were forced to retain an attorney to pursue their claim for insurance benefits. On August 18, 2016, the Chad T. Wilson Law Firm filed suit, on behalf of our client, against Scottsdale Insurance Company and Wardlaw Claims Service LLC for fraud, breach of contract, negligence, gross negligence and violations of the Texas Insurance Code and the Texas DTPA.

Texas Property Insurance Lawyers

If your homeowner insurance carrier has denied your insurance claim, we can help. The experienced property insurance attorneys at Chad T. Wilson Law Firm have represented more than 1,000 clients in cases against insurance companies and aggressively protect the rights of insurance policyholders throughout Texas. Our consultations are free, and you owe us nothing until your case is won. Contact us today to see how we can help.

1 2 3 4 5